Market overview of the Military Satellite Communications Market
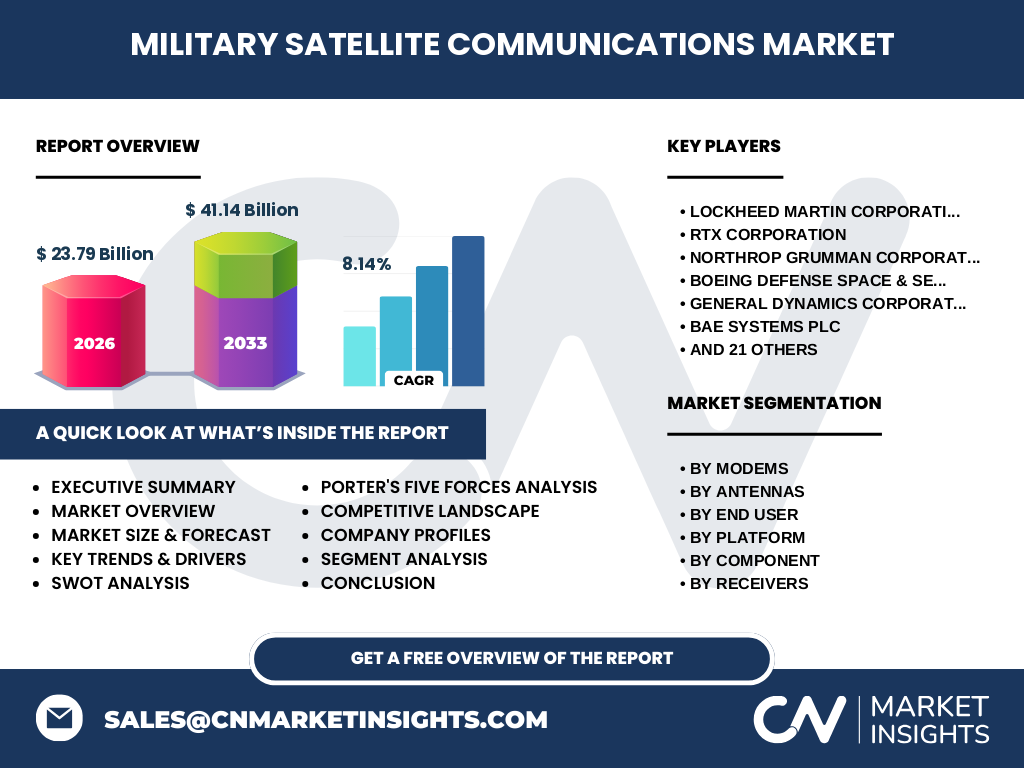
Our analysis indicates the Military Satellite Communications Market reaches $23.79 Billion in 2026, driven by critical defense infrastructure demands. This sector encompasses secure transponders, advanced modems, and phased array antennas deployed across airborne, ground, naval, and space domains to ensure resilient, jam-resistant tactical communications during high-stakes geopolitical engagements.
What are the core drivers, restraints, and opportunities shaping the Military Satellite Communications Market?
Structural growth is propelled by escalating asymmetric warfare threats and space domain militarization. However, severe supply chain bottlenecks for critical Gallium Nitride (GaN) semiconductor raw materials and strict ITAR export restrictions act as primary restraints. Significant opportunities emerge in commercial-off-the-shelf (COTS) integration for agile, multi-orbit constellations.
Emerging trends and growth patterns in the Military Satellite Communications Market
The shift toward multi-orbit architectures and Software Defined Receivers (SDRs) defines current industry dynamics. Military agencies increasingly demand interoperability across Ultra High Frequency, Super High Frequency, and Ka-Band spectrums, forcing innovators like Kratos Defense & Security Solutions Inc. and Viasat Inc. to pioneer flexible, software-driven terminal payloads.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain disruptions and component shortages for vital power supply units and encryption modules. Despite these logistical hurdles, the sector experienced rapid recovery as defense ministries accelerated digital transformation budgets, prioritizing resilient, cloud-connected tactical communication modems over legacy hardware.
Competitive benchmarking and strategic dynamics in the Military Satellite Communications Market
Market concentration remains high among prime aerospace contractors such as Lockheed Martin Corporation, Northrop Grumman Corporation, and Boeing Defense Space & Security. These giants leverage vertical integration across high throughput transponders and airborne platforms, while agile disruptors like SpaceX Corp. and Eutelsat OneWeb challenge traditional defense procurement models.
Executive summary of key findings for the Military Satellite Communications Market
Our research projects the Military Satellite Communications Market to expand from $23.79 Billion in 2026 to $41.14 Billion by 2033, registering a robust 8.14% CAGR. Strategic investments in flat panel antennas and high power transmitters will dictate long-term market leadership and profitability.
Market forecast from 2027 to 2033
Propelled by surging demand for Intelligence, Surveillance, and Reconnaissance (ISR) applications, the market is poised for accelerated expansion. Reaching $41.14 Billion by 2033 at a 8.14% CAGR, growth will be heavily concentrated in secure X-band and Ka-band tactical networks deployed by allied defense forces worldwide.
Segmentation analysis across modems, antennas, and platforms
The market segments intricately by hardware and application. Modems cover satellite, broadband, secure, and tactical variants. Antennas feature parabolic, phased array, flat panel, and deployable units. Platforms span airborne, ground, naval, and space domains, each requiring specialized transponders, frequency bands, and ruggedized encryption modules.
Regional market analysis and geographic performance
North America dominates the global landscape due to massive Department of Defense modernization budgets and the active presence of prime innovators like L3Harris Technologies Inc. and RTX Corporation. Meanwhile, the Asia-Pacific region demonstrates the fastest regional growth rate, spurred by escalating maritime territorial disputes and increased defense outlays.
In-depth regional review of key defense corridors
European markets focus heavily on sovereign secure communication networks governed by the European Defence Agency (EDA), favoring regional champions like Thales Group, Airbus Defence and Space, and Leonardo S.p.A. Concurrently, Middle Eastern and Indo-Pacific nations prioritize resilient ground and naval terminals to counter advanced electronic warfare threats.
Company profiles and strategic positioning of market leaders
Industry leaders employ distinct strategies to capture market share. Israel Aerospace Industries (IAI) and Elbit Systems Ltd. focus on battle-tested tactical transmitters, while Kymeta Corporation and ThinKom Solutions Inc. pioneer flat panel antenna technologies essential for mobile military platforms operating under extreme environmental constraints.
Porter's Five Forces analysis of the Military Satellite Communications Market
Bargaining power of buyers is moderate to high, dominated by well-funded national defense ministries exerting strict pricing controls. Threat of new entrants remains low due to prohibitive capital expenditure requirements, stringent military certification standards, and complex security clearances for handling classified encryption modules.
SWOT analysis of the Military Satellite Communications Market
Key strengths include unmatched global connectivity and robust tactical security. Weaknesses involve high payload launch costs and complex integration hurdles. Opportunities lie in commercial mega-constellation partnerships, while threats stem from sophisticated orbital anti-satellite (ASAT) capabilities and electronic jamming by hostile nation-states.
Value chain analysis from raw materials to end-users
The value chain initiates with raw semiconductor materials like Gallium Arsenide, progressing through specialized component manufacturers (such as WORK Microwave GmbH and Satcube AB) producing transponders and signal processors. Prime integrators then assemble these into turnkey airborne and ground terminals for end-users in defense and homeland security.
Investment insights and high-potential areas
Strategic investors should prioritize firms specializing in flat array antennas, software defined receivers, and quantum-resistant encryption modules. Companies bridging commercial low Earth orbit (LEO) constellations with legacy military ground infrastructure present the highest risk-adjusted return profile over the forecast window.
Conclusion and key takeaways for stakeholders
The Military Satellite Communications Market offers compelling growth, advancing from $23.79 Billion to $41.14 Billion by 2033. Success requires navigating stringent regulatory compliance, mastering multi-orbit interoperability, and forging strategic partnerships between traditional defense primes and agile commercial satellite innovators like Gilat Satellite Networks and C-COM Satellite Systems Inc.
Research methodology for baseline estimation
Our proprietary methodology triangulates data from global defense trade registries, primary stakeholder interviews with chief technology officers, and secondary macroeconomic indicators. Quantitative models cross-reference military budget allocations with historical procurement cycles to ensure precise market sizing and growth projections.
Scope of the report and coverage parameters
This report covers global military satellite communications deployment across airborne, ground, naval, and space domains through 2027 to 2033. Limitations include the exclusion of purely civilian commercial telecom payloads and classified black-budget defense programs that lack verifiable public disclosure.
Recent developments, partnerships, and strategic moves
Recent industry momentum is defined by strategic acquisitions and cross-border defense partnerships. Firms like Cobham Satcom and Intellian Technologies Inc. have ramped up production of ruggedized multi-band terminals, while GomSpace Group AB secures vital contracts for micro-satellite constellations designed to enhance tactical battlefield resilience.